Most people think a personal loan is a magic wand for a broken furnace or a sudden medical bill. In reality, it’s just a high-interest bet against your future self. You aren’t making money; you’re just moving debt from one category to another, usually with a fee attached for the privilege.
If you’re sitting in a Milwaukee coffee shop or a Madison kitchen staring at a pile of bills, you probably feel like you need a miracle. You don’t. You just need to understand the math before you sign a contract that treats your paycheck like an all-you-can-eat buffet for a lender.
Wisconsin isn’t a vacuum. The rules here are specific, the lenders are varied, and the difference between a “good” loan and a trap is often just a single decimal point in your APR. You need to know which side of that decimal you’re on before you walk into a branch.
The Milwaukee Loan Spectrum: From Credit Unions to Payday Traps
Not all debt is created equal, even if the bank teller smiles the same way regardless of your credit score. In Milwaukee, you’ll run into a massive spectrum of options ranging from the genuinely helpful to the predatory. It’s a wide gap, and falling into the wrong end can take years to climb out of.
On one end, you have credit unions. These are member-owned cooperatives that actually care about their community because they are part of it. If you have a decent credit history, these institutions offer much more humane terms than the storefront lenders in strip malls.
For example, Prime Financial Credit Union offers unsecured personal loans with rates as low as 10.90% APR and terms that can stretch up to 48 months. That’s a massive difference compared to the high-interest products from payday lenders. If you can prove you’re a reliable human being, go for these rates rather than settling for whatever is closest to your house.
The High Cost of “No Credit Check”
Then there is the “no credit check” crowd. These lenders market heavily to people who are desperate. They promise speed and ease, but they charge for that convenience with interest rates that make a credit card look like a charity donation. You might get the cash today, but you’ll be paying for that speed for the next two years.
If you find yourself looking at a “no credit check” loan, you are essentially paying a premium to be ignored. It’s a short-term fix that often creates a long-term cycle of debt. You might get $1,000 in twenty-four hours, but the math rarely works out in your favor in the long run.
Navigating the Digital Application Maze
The days of sitting in a waiting room reading a 2014 magazine are mostly over. Most of the work happens on your phone while you’re sitting on your couch. This is convenient, but it also means you can make a catastrophic mistake with three taps of your thumb before you’ve even had your morning coffee.
Digital lenders want you to move fast. They want the application to feel painless. But “painless” is a marketing term, not a financial reality. You need to slow down. If a lender makes it too easy to skip the fine print, that’s usually a sign the fine print contains something you won’t like.
Look for lenders that allow you to prequalify online. This is a low-stakes way to see what you might qualify for without a hard inquiry hitting your credit report. It’s a way to “window shop” for debt. If you can see the terms before you commit, you’re already ahead of half the people in the state.
Many people use sites like Wiscloans to compare how different lenders stack up. It’s better to spend twenty minutes comparing APRs now than spending twenty months paying off a loan you didn’t actually need because you were in a rush to cover a car repair.
Is it easier to get a loan online? Yes. Is it safer? Not necessarily. It depends on whether you’re actually reading the terms or just clicking “I agree” to get to the next screen.
Comparing the Real Numbers in Wisconsin
If you want to understand the situation, stop looking at the monthly payment and start looking at the total cost of the loan. A $500 monthly payment sounds manageable, but if that payment lasts for five years because the interest rate is astronomical, you aren’t paying for a car; you’re paying for the lender’s new yacht.
The following table shows why looking at the APR is the only way to actually compare two different offers. A lower monthly payment might seem attractive, but it often hides a longer term that costs you more in the end.
| Loan Feature | Standard Bank Loan | Credit Union Loan | Predatory/Payday Loan |
|---|---|---|---|
| Typical APR | 8% – 15% | 6% – 18% | 30% – 400%+ |
| Ease of Approval | Moderate (Credit Check) | Moderate (Credit Check) | Very High (No Check) |
| Long-term Impact | Builds Credit | Builds Credit | Destroys Credit |
When comparing lenders, look at three things: the APR, the origination fees, and the prepayment penalties. Some lenders charge you a fee just for the “privilege” of taking their money. Others will punish you if you try to pay the loan off early by charging you a penalty for being responsible. Avoid those. There is no reason to pay a fee for being efficient.
You also need to check if the lender is actually licensed to operate in Wisconsin. A state-licensed direct lender is much more likely to follow consumer protection laws than a shady outfit operating out of a generic web domain. If they won’t tell you exactly where their headquarters is, walk away.
The Trap of “Flexible” Terms
Lenders love the word “flexible.” It sounds friendly, like they’re doing you a favor. In reality, “flexible” often means they can change the terms or offer you a “repayment plan” that’s actually just a way to keep you in debt longer while more interest accrues.
True flexibility is having the option to pay extra toward your principal without being penalized. That’s the only kind of flexibility that actually helps you. Anything else is just a gimmick designed to make the debt feel less heavy while it pulls you under.
The 2026 Outlook: What to Expect as Rates Shift
The economic environment in Wisconsin is shifting, and that affects how much it costs you to borrow money. As we move through 2026, interest rates will dictate whether a personal loan is a sensible tool or a financial disaster. You can’t borrow money in a vacuum; you’re borrowing money that someone else is also trying to borrow.
If inflation is high, interest rates usually follow. This means the “good” rates you see today might be gone by next month. You have to time your borrowing carefully, which is hard when you have an urgent need for cash. If you can wait, you should. If you can’t, you need to be extremely selective about who you borrow from.
A lot of people are looking at the top providers in the state to see who is offering the best deals. It’s a smart move to compare APR, fees, and repayment costs before you commit. You should be looking at the total cost of your loan, not just the shiny number on the advertisement. It’s a messy process that requires you to actually do the math, but it’s the only way to ensure you don’t end up in a hole you can’t climb out of.
The market is moving toward more digital-first lending, but the traditional banks and credit unions still hold the best cards. Don’t let the convenience of a mobile app trick you into thinking that a high-interest rate is “easy.” It’s actually just expensive.
Watch the Federal Reserve closely, because their decisions will eventually determine whether you’re paying 7% or 17% for that next car repair.
Quick answers
Are personal loans hard to get?
Approval depends on your credit score, income, and debt-to-income ratio, but many lenders offer options for various credit profiles.
What is the best bank in Wisconsin?
The best bank depends on your needs, but major institutions like Chase and BMO are popular, while local credit unions often offer better rates.
How do payday loans work?
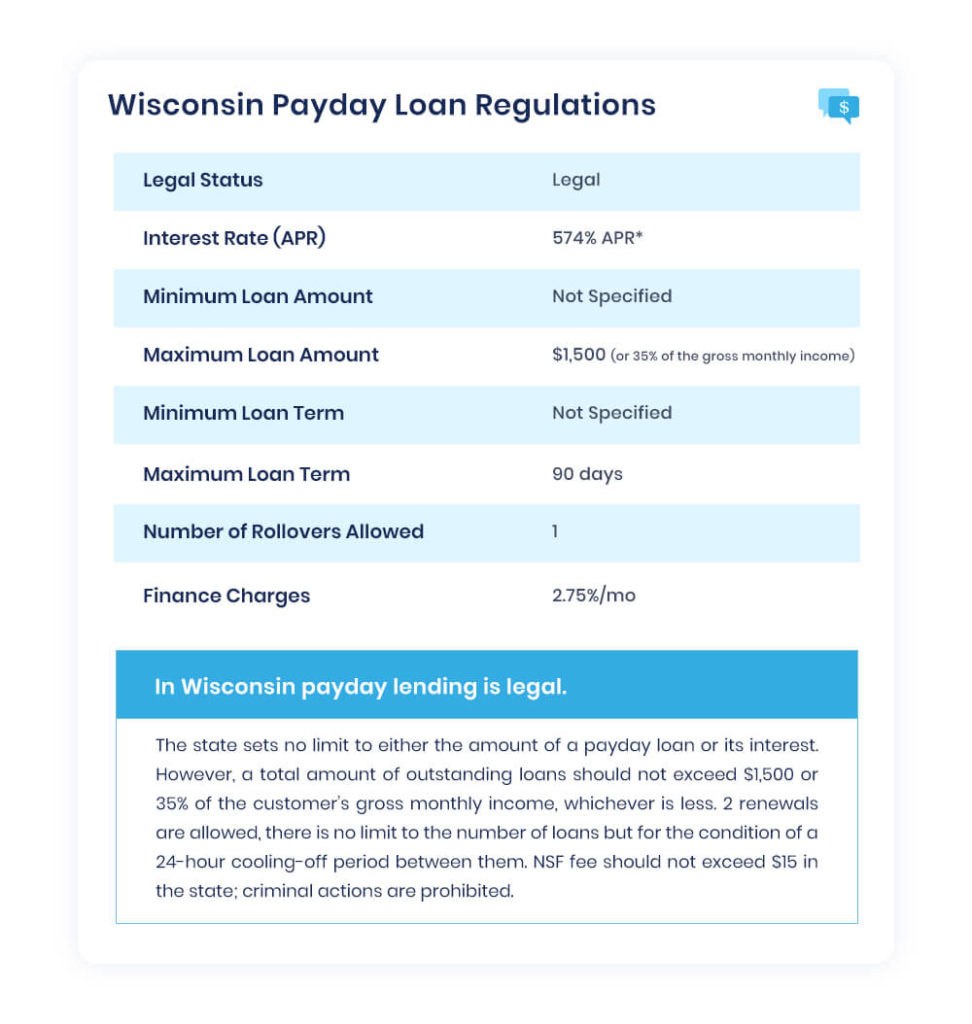
Payday loans are short-term, high-interest loans meant to be repaid by your next paycheck, often carrying extremely high APRs.
Can I get a $100 loan without a credit check?
While some lenders offer small, no-credit-check loans, they typically come with very high interest rates and unfavorable terms.
What are the requirements for a personal loan in Wisconsin?
Generally, you must be at least 18 years old, a resident of Wisconsin, and have a steady source of income to qualify.